ICTSI 9M profit rises 20% as port revenue grows
New terminals drove much of the 13% throughput increase across the group.
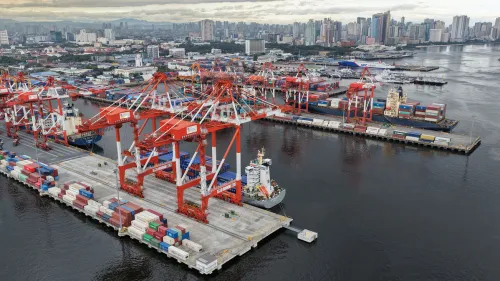
The International Container Terminal Services, Inc. (ICTSI) reported a 20% increase in nine-month (9M) net income attributable to equity holders to $898.89m, driven primarily by higher operating income.
For the third quarter (Q3), net income rose 15% to $308.90m.
Excluding the nonrecurring charge from the sale of Yantai International Container Terminal (YICT) in Shandong Province, China, net income would have grown 22% to $913.59m.
Revenue from port operations increased 24% to $2.90b in 9M, whilst Q3 revenue rose 19% to $984.05m.
The increase was mainly driven by volume growth with a favourable container mix, higher revenue from ancillary services and tariff adjustments at certain terminals, alongside contributions from Durban Gateway Terminal (DGT) and Batu Ampar Container Terminal (BACT).
Earnings before interest, taxes, depreciation and amortisation (EBITDA) rose 21% to $1.87b in 9M, whilst Q3 EBITDA increased 15% to $635.74m.
Diluted earnings per share increased 21% to $0.442 in 9M.
ICTSI handled 12,114,429 twenty-foot equivalent units in 9M, up 13%, driven mainly by contributions from DGT and BACT.
Volumes were also supported by improved trade activity in Asia and the Americas, partially offset by volume decreases at certain terminals in EMEA, mainly at Basra Gateway Terminal in Iraq due to geopolitical conflict in the Middle East, and the deconsolidation of YICT.
Excluding volume contributions from DGT and BACT and discontinued operations at YICT, consolidated volume would have marginally increased by 0.1%.
Consolidated cash operating expenses increased 37% to $801.40m in 9M.
This was driven by cost contributions from DGT, volume- and revenue-driven increases in operating expenses, government-mandated and contracted salary rate adjustments, and unfavourable foreign exchange effects.
These increases were partially offset by continuous cost optimisation measures and favourable foreign exchange effects on PHP-based expenses.
Excluding the impact of new and discontinued operations, consolidated cash operating expenses would have increased by 16%.
EBITDA margin declined to 64% from 66%, primarily reflecting the impact of integrating newly acquired operations.
Excluding new and discontinued operations, EBITDA would have increased by 15%, whilst EBITDA margin would have improved slightly to above 66%.
ICTSI's capital expenditures, excluding capitalised borrowing costs, stood at $507.43m in 9M.
The company estimates 2026 capital expenditures at $740m, mainly for the completion and expansion of terminals, equipment acquisitions and upgrades, maintenance, and other expansion projects.